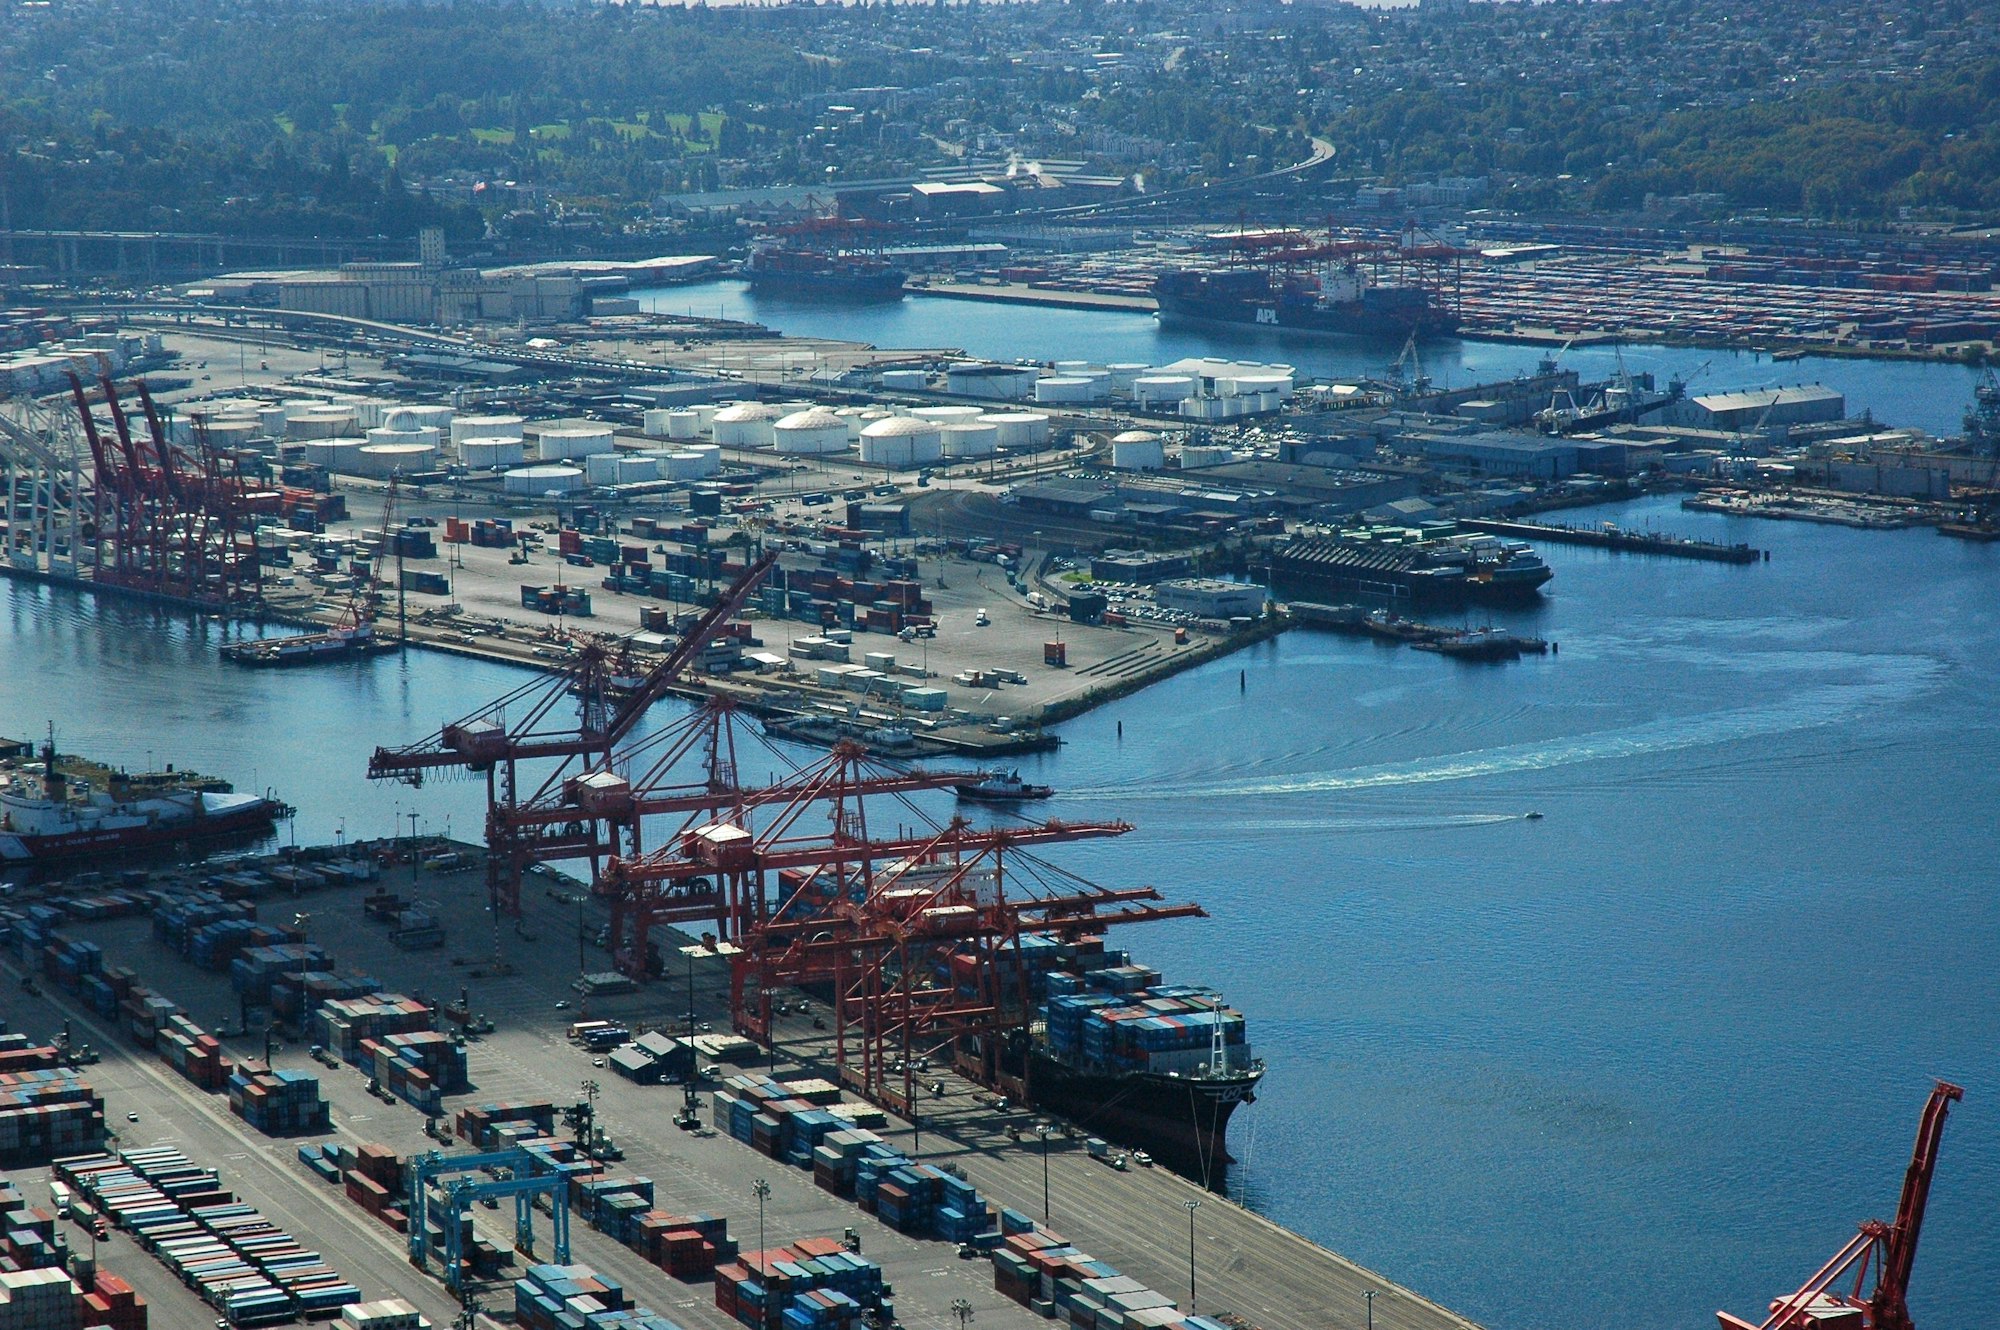
Last October the promotional products industry was bracing for a rough fourth quarter. Imports were already falling: the National Retail Federation’s port tracker had September volumes down 7.4% from a year earlier, after months of retailers pulling orders forward to get ahead of tariffs that kept changing (NRF). Then in February the Supreme Court ruled that the emergency-powers law behind the country-by-country tariffs doesn’t authorize tariffs at all (opinion). Within days the administration replaced them with a temporary 10% duty on most imports (White House). Since late July a Section 301 structure has put most trading partners at 10% or 12.5% (USTR). For most suppliers the rates sit well below last year’s peaks, but the legal authority behind them has changed twice in a year, which is its own kind of uncertainty.
Demand moved too. Several suppliers have reported rising interest in U.S.-made products tied to America’s 250th anniversary, and PPAI reported one supplier’s domestic production up more than 30% (PPAI). ASI’s search data is less tidy. This spring, searches for patriotic products more than doubled, while searches using the Made-in-USA filter fell year over year (ASI). My read is that buyers want the occasion more than the country of origin, though a domestic-made item does land differently this fall than it would have a year ago. The practical catch is timing, since domestic production schedules don’t compress the way overseas ones sometimes can when a deadline gets tight.
The more durable point from earlier this year still holds: fewer, better items beat a pile of forgettable ones. That has moved from a preference of companies trying to look thoughtful on a budget to the industry’s own stated direction. Heading into this year, PPAI’s consumer research described people as wanting fewer products that are better designed and more meaningful (PPAI). The instinct to order in bulk because a per-unit price looks good is the instinct tariff volatility keeps punishing. A warehouse of unsold trinkets is a worse outcome than a smaller order of things people keep.
If I were planning Q4 merch now, I’d order earlier than feels necessary, since domestic and reliable overseas production both have less slack than they used to. I’d spend more per unit on fewer items someone will still be using in February. I’d also treat the sourcing conversation as part of the decision rather than paperwork that follows it, because who makes the thing and how it reaches you now matters nearly as much as what the thing is.
I pay closer attention to this category than most marketing practices do. Partly that’s because Cedar Collaborative has a sister company in the space, and partly it’s because merch is one of the few marketing line items a client can hold in their hands and judge in about two seconds. Most marketing spend never faces a test that immediate. That’s a reason to plan for it well before the order has to go in, and possibly a reason to ask why so much of the rest of the budget escapes the same scrutiny.