The past few months have felt like a flashback to 2018, except much faster, clearer, and less fun.
In 2018, many of us braced for a recession that never came. That quiet preparation, tightening budgets, strengthening systems, trimming nice-to-haves, became invaluable when the 2020 pandemic arrived. This time the warning lights are brighter, the market signals are harder to read, and the policy noise is louder and faster.
What’s happening now
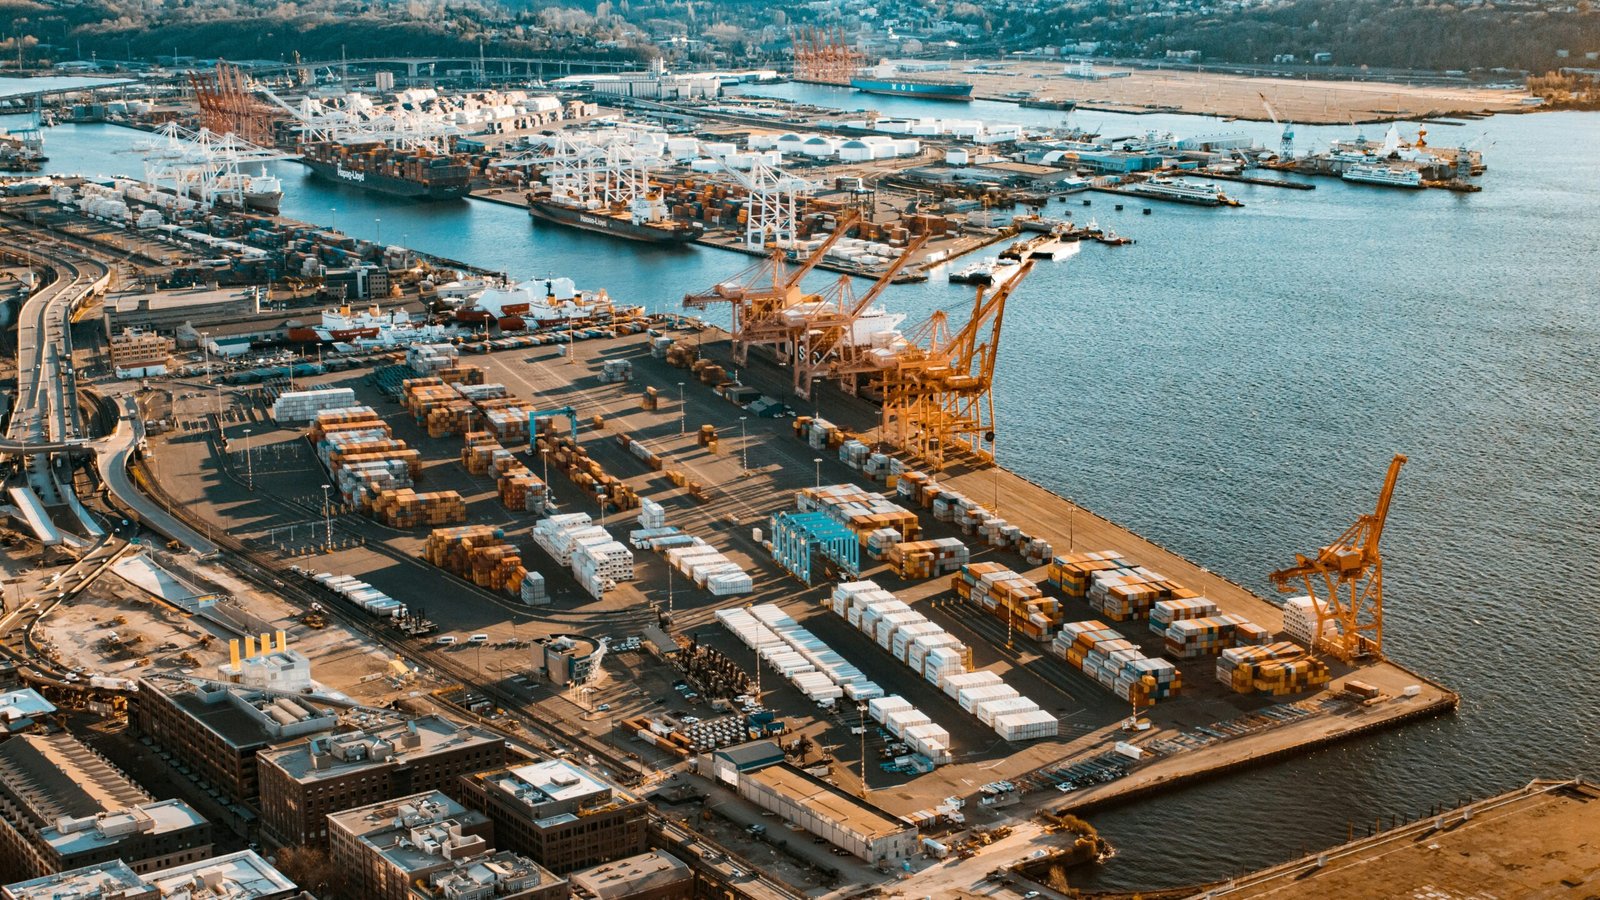
The sudden removal of senior U.S. economic officials has shaken trust in the data business leaders rely on. On-again, off-again tariffs as high as 145 percent are disrupting supply chains across manufacturing, technology, and logistics. Swings in the U.S. dollar, combined with retaliation from trading partners, are adding uncertainty to markets that once felt more stable (see the IMF World Economic Outlook, July 2025). Policy shocks like this aren’t background noise: in politically volatile periods, they can trigger investment freezes and supply chain delays within weeks (also worth checking the World Bank Global Economic Prospects, June 2025).
What I’m hearing
Startups and small manufacturers are split on inventory: some buying ahead to beat price hikes, others holding back to avoid costly overstock, while prices steadily creep up to cover the new costs either way. Expansion plans are getting delayed over fears that currency shifts will erase projected gains, and the ones that do move forward now price in currency instability and increasingly avoid taking payment in non-USD denominations. And spending is pivoting: founders are shelving merch programs, sales team growth, and ad campaigns in favor of slower, steadier options like SEO, automation, and inbound content.
These moves track what economists have been watching since late 2024: rising input costs, tighter credit, and falling confidence among consumers and business owners alike (the OECD Economic Outlook is worth watching for these short-term trends).
Why this spreads beyond the U.S.
The U.S. economy doesn’t operate in isolation. When it contracts or hesitates, the effects reach well beyond its borders. Canada feels it in manufacturing inputs and export demand, often before domestic indicators turn. Australia faces a double bind, with trade exposure to both the U.S. and China and currency movements that can shift export profitability within days. The UK experiences it through shifts in investor sentiment, particularly in financial services and manufacturing order volumes. International nonprofits see it in reduced U.S.-based grants and donations. For leaders outside the U.S., the lesson is to prepare for impacts that may arrive more slowly but are no less certain, and in some cases to act before the local headlines catch up.
The real damage
The problem is the erosion of trust, not just tariffs or currency instability. When the reliability of official data gets questioned, strategy shifts from deliberate to reactive. For early-stage companies, stability is already scarce, and hesitation replaces innovation while the cost of waiting quietly compounds.
What remains in our control
Watching costs closely, strengthening supplier relationships, and investing in systems that give leaders real options all still matter, and a real-time dashboard is worth more now than it was a year ago. Practical solutions tend to beat flawless ones that arrive too late. And mapping best, middle, and worst cases is worth doing on its own terms: preparing for each scenario is an act of optimism, since it assumes there will still be a business here to make those calls.
If there’s one thing worth doing this quarter, it’s auditing the top three suppliers or partners for tariff and currency exposure, and reviewing which marketing channels could activate quickly if conditions shift. A few hours of work now can save weeks of delay later.
I don’t claim to have all the answers. I’ve seen enough to know that steady preparation is the best counter to disorder. The companies making those plans now will be the ones ready to move once the noise fades. This is the current picture. The playbook comes next.